

ebtEDGE NEW!
3.2

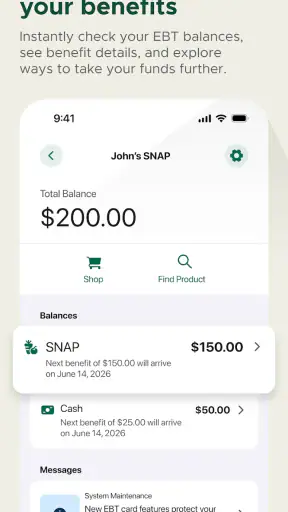
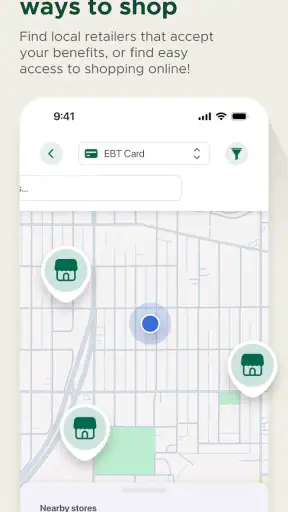
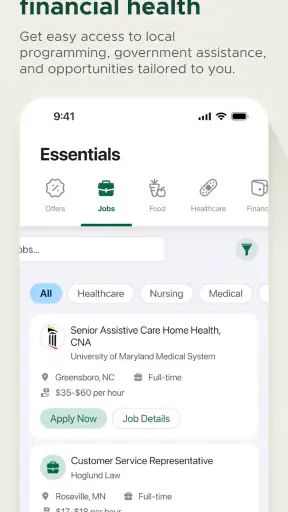
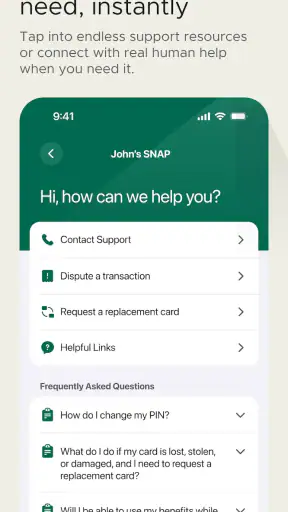
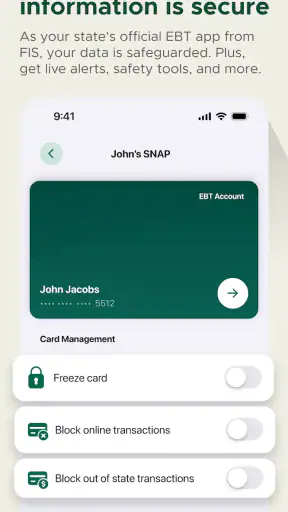
Managing public benefits is rarely a one-time task. I may need to check a balance before shopping, confirm whether a recent purchase went through, or keep track of several benefit programs without carrying extra paperwork. That is the practical space where ebtEDGE NEW! fits. It is a free finance app from Fidelity Information Services LLC, designed for SNAP, Childcare, and WIC benefits in participating states.
My first impression is that its value is less about novelty and more about reducing small moments of uncertainty. The app is not trying to replace a full banking service, budgeting platform, or shopping tool. Its job is narrower: give benefit recipients a mobile place to manage information connected with their state benefits. That focus is useful, but it also means the experience depends heavily on whether its state support and account access match your situation.
The app is listed for everyone, has reached over one hundred thousand installs, and carries an average rating of 3.2 from around six hundred ratings. Those figures suggest a tool with a real audience but also an uneven experience for some users. I would approach it as a practical utility rather than an app I expect to enjoy using. If it reliably answers the questions I have before or after a purchase, it earns its place on my phone.
What the first week feels like
Useful immediately when the right state is supported
The strongest first-week appeal is straightforward access. Instead of relying on a browser bookmark, a printed notice, or a phone call every time I want to review my benefits, I can start with a dedicated mobile app. That matters most when I am already away from home. A quick check before reaching the checkout can help me decide whether to use benefits now, postpone a purchase, or separate eligible items from other groceries.
A realistic example is a parent shopping after work with a WIC or SNAP balance in mind. The phone becomes a planning aid rather than just a place to receive alerts. I can check the relevant account before loading a cart, then review the result afterward if the total looks different from what I expected. That simple before-and-after habit is more useful than opening the app only when something has gone wrong.
The app’s official role is important here. It is intended for SNAP, Childcare, and WIC benefits in your state, so I would begin by confirming that my state and benefit program are represented during setup. This is the first practical question a new user should answer. If the app does not connect to the program I actually use, its cleanest interface would not make it worthwhile.
Setup is part of the test
During the first week, I would not judge the app only by how quickly it opens. I would test whether I can sign in consistently, find the correct benefit account, and understand the information shown without guessing. Benefit apps have a higher cost of confusion than ordinary shopping apps: an unclear screen can affect a grocery trip, childcare planning, or a household budget.
I would also keep my state-issued card and account details nearby during setup. That is not glamorous advice, but it prevents the common mistake of treating registration as something that can be completed casually while standing in a checkout line. A better workflow is to install the app at home, sign in carefully, and then open it again later when I am not under pressure. The second opening tells me whether the app has become a dependable tool or merely a first-day experiment.
The current version is 4.0.0, and the app supports devices running Android 7.0 or later. That broad operating-system range may help people using older phones, although compatibility alone does not guarantee that every screen will feel equally comfortable on every device. I would keep the app updated when an update is available, particularly for a finance-related service where access and account display matter more than visual novelty.
What I would learn before relying on it
One useful first-week exercise is to map the app to three questions: what is available, what has recently happened, and what I need to do next. If the app answers those questions clearly, it can become part of a routine. If I still need to call a state office or search through old messages for basic account context, I would treat it as a secondary tool rather than my only source of information.
I would not assume that the app replaces every official channel. A mobile view can be convenient, but benefit rules, eligibility decisions, case changes, and program-specific questions may still belong to the responsible state agency. The app is most convincing when I use it for day-to-day visibility and use official support channels for issues that require a decision, correction, or explanation.
Why it may still matter after the first month
Recurring value comes from small checks
After the initial curiosity fades, the question becomes whether I open the app without being reminded. For me, that depends on whether it supports a repeatable routine. Checking before a planned grocery trip, reviewing activity after shopping, and looking again before the next benefit cycle are small actions, but they can prevent larger surprises. The app does not need to dominate my day to be useful; it needs to be dependable at the moments when the information matters.
This is where a dedicated benefits app has an advantage over a general budgeting app. A budgeting app may show cash spending, bank transactions, or manually entered expenses, but it is not necessarily built around SNAP, WIC, or Childcare benefits. A bank app can be excellent for checking a checking-account balance, yet it may not provide the same benefit-specific context. A web portal may offer similar information, but opening a browser, finding the correct page, and signing in repeatedly can create enough friction that I postpone the check.
The trade-off is that ebtEDGE is not a complete household money manager. I would not use it to replace a monthly budget, track every bill, compare bank accounts, or plan debt payments. Its lasting value is narrower and clearer: it can sit alongside those tools as the place I consult for supported benefit information.
A better habit than checking only after a problem
Many people open a benefits app only when a transaction seems wrong. That makes every visit stressful and gives the app little chance to become familiar. I would instead check it at calm times. For example, I might review the account before making a shopping list, then compare the expected purchase with the activity afterward. Over time, this creates a personal reference point for how quickly information appears and which details are most useful to me.
That workflow also helps separate two different problems. A balance question may be answered by the app, while a declined transaction or missing benefit may require the card issuer, retailer, or state agency. Knowing that distinction prevents me from repeatedly refreshing the same screen when the real solution lies elsewhere. The best long-term use is informed checking, not endless checking.
Different households will get different value
The app is especially well suited to someone who manages benefits while moving between home, work, school, and stores. It can also help a caregiver who needs a quick view of a supported account without keeping paper records in several places. For a household that shares shopping responsibilities, having a consistent place to check information may reduce misunderstandings about what is available.
On the other hand, a person who rarely uses a smartphone, has unreliable internet access, or prefers speaking with an agency representative may not gain much from adding another digital account. Someone who uses only a benefit program that is not supported in their state should skip the app rather than forcing it into a workflow. The same is true for a user expecting detailed financial planning: this is not the right category of tool for that job.
The maintenance burden of keeping it useful
It should be low effort, but not ignored
A good utility app earns long-term space by asking little from me between important moments. I would keep notifications and account settings organized, but I would avoid treating every alert as urgent until I understand what it refers to. If the app presents account activity clearly, occasional checks may be enough. If I have to repeatedly sign in, interpret unclear messages, or verify whether information is current, the maintenance burden rises quickly.
There is also a practical device issue. People often keep older phones for as long as possible, especially when replacing a phone competes with groceries or household costs. Support for Android 7.0 or later is helpful for compatibility, but I would still check that the phone has enough storage, a working connection, and a current version of the app. If the app behaves poorly on a particular device, the problem may be the phone or connection rather than the account itself, so I would test it in a stable environment before drawing conclusions.
Keep a backup path for important moments
I would not make the app my only plan on a day when a benefit payment or purchase is especially important. Keeping the state’s official contact route available is sensible, as is retaining the physical benefit card and knowing where to get help if the app cannot display what I need. This is not a criticism unique to ebtEDGE; mobile access can fail because of a device, connection, sign-in issue, or service interruption.
A useful maintenance habit is to review the account when I am not standing at a register. If something looks unfamiliar, I have time to investigate instead of trying to solve it while other shoppers wait. I would also avoid sharing login details with family members simply to make shopping easier. A shared household may need a clear arrangement, but account access should remain deliberate and secure.
Updates should be judged by reliability
With a financial app, I care more about stable access and understandable account information than a redesigned icon or a new visual style. The developer, Fidelity Information Services LLC, places this app in a sensitive area where reliability matters. When an update arrives, I would open the app afterward and confirm that I can still reach the account and find the screens I use most. That small check is worthwhile because a change that seems minor can disrupt a routine built around shopping or childcare planning.
I would also resist deleting the app just because I do not use it every day. A benefits utility may be quiet for several days and then become important within minutes. Its value is not measured by screen time. The better question is whether it is ready when I need a current view of supported benefits.
Where fatigue can set in
Repeated friction changes the verdict
The main danger for long-term use is not that the app is too complicated; it is that small obstacles may become tiring. If sign-in takes too long, if the correct program is hard to locate, or if the displayed information does not answer the question I brought to the app, I may return to a browser or phone call. A tool that saves time once but costs time every week will eventually lose its place on my home screen.
The average rating of 3.2 indicates that the experience is not uniformly smooth for everyone. I would read that as a reason to test the app against my own state, device, and benefit needs rather than assuming either universal success or universal failure. A rating cannot tell me whether another user had a state-specific issue, a login problem, or a mismatch between expectations and the app’s purpose. My own first-week test is more useful than treating the average as a guarantee.
It is not a substitute for human resolution
Another source of fatigue appears when people expect the app to solve administrative problems. If a case needs correction, a benefit decision must be explained, or a card issue requires intervention, repeatedly opening the app may only confirm that the problem remains. In those situations, I would use the app to gather the information it does show, note relevant activity, and then contact the appropriate official channel.
This distinction also matters for WIC and Childcare users, whose needs may not look identical to those of SNAP users. A household may move between programs or manage more than one type of benefit, and the most useful screen may change from one month to the next. I would judge the app by whether it keeps those supported tasks understandable, not by whether it behaves like a general-purpose finance dashboard.
When another option is better
A state web portal may be better for someone who prefers a larger screen or needs to read more detailed administrative information. A phone call may be better when the issue is urgent, personal, or not represented clearly in the app. A general budgeting app may be better for planning rent, utilities, savings, and cash spending. None of those alternatives makes ebtEDGE pointless; they simply serve different jobs.
I would skip it if my benefit program or state is not supported, if I cannot maintain reliable access to the account, or if I need a full financial overview rather than benefit-specific visibility. I would also be cautious about recommending it as the sole tool for a caregiver who cannot afford uncertainty at checkout. In that case, the app can be useful alongside a backup method, but dependence on one mobile screen would be too risky.
My long-term verdict
After the first-week appeal wears off, ebtEDGE earns lasting space only when it becomes part of a simple habit: check before a planned purchase, review after an important transaction, and use the proper official channel when the issue goes beyond account visibility. That is a modest promise, but it is a meaningful one for people who manage SNAP, WIC, or Childcare benefits through a supported state program.
I like the focused purpose. The app does not need to imitate a bank or a budgeting suite to be useful, and its free price removes one obvious barrier to trying it. The everyone age rating also makes it broadly approachable, although ease of access should not be confused with suitability for every state or every household workflow. Its strongest quality is convenience at the exact moment when a current benefit view can make a shopping decision less stressful.
My reservations are equally practical. The 3.2 average suggests that I should not install it blindly and assume a perfect experience. I would verify state support, complete setup away from a checkout line, test the account more than once, and keep a backup route for urgent questions. Those steps are not excessive for a finance app; they are what turn a potentially frustrating download into a dependable routine.
Overall, I would recommend ebtEDGE NEW! to eligible users who want a dedicated mobile way to review supported benefits and are comfortable pairing it with official assistance when an administrative problem appears. I would not recommend it as a replacement for a budget, a bank app, or human support. Its long-term value is quiet and recurring rather than exciting: fewer guesses before shopping, a clearer check afterward, and one less piece of benefit information to manage from memory.
3.2
390.00 Reviews
Pros
- Quickly checks EBT balances and recent transactions
- Supports multiple benefit accounts in one place
- Provides purchase and deposit activity details
- Offers convenient access while away from a computer
- Helps monitor benefits and spot unfamiliar transactions
Cons
- Availability and features may vary by state
- Requires an internet connection for most functions
- Users may need to reverify identity after updates
- Transaction information can sometimes take time to refresh
- Some users may find the interface less intuitive at first


